ServicesHotshot Truck Insurance
Hotshot Truck Insurance in Denton
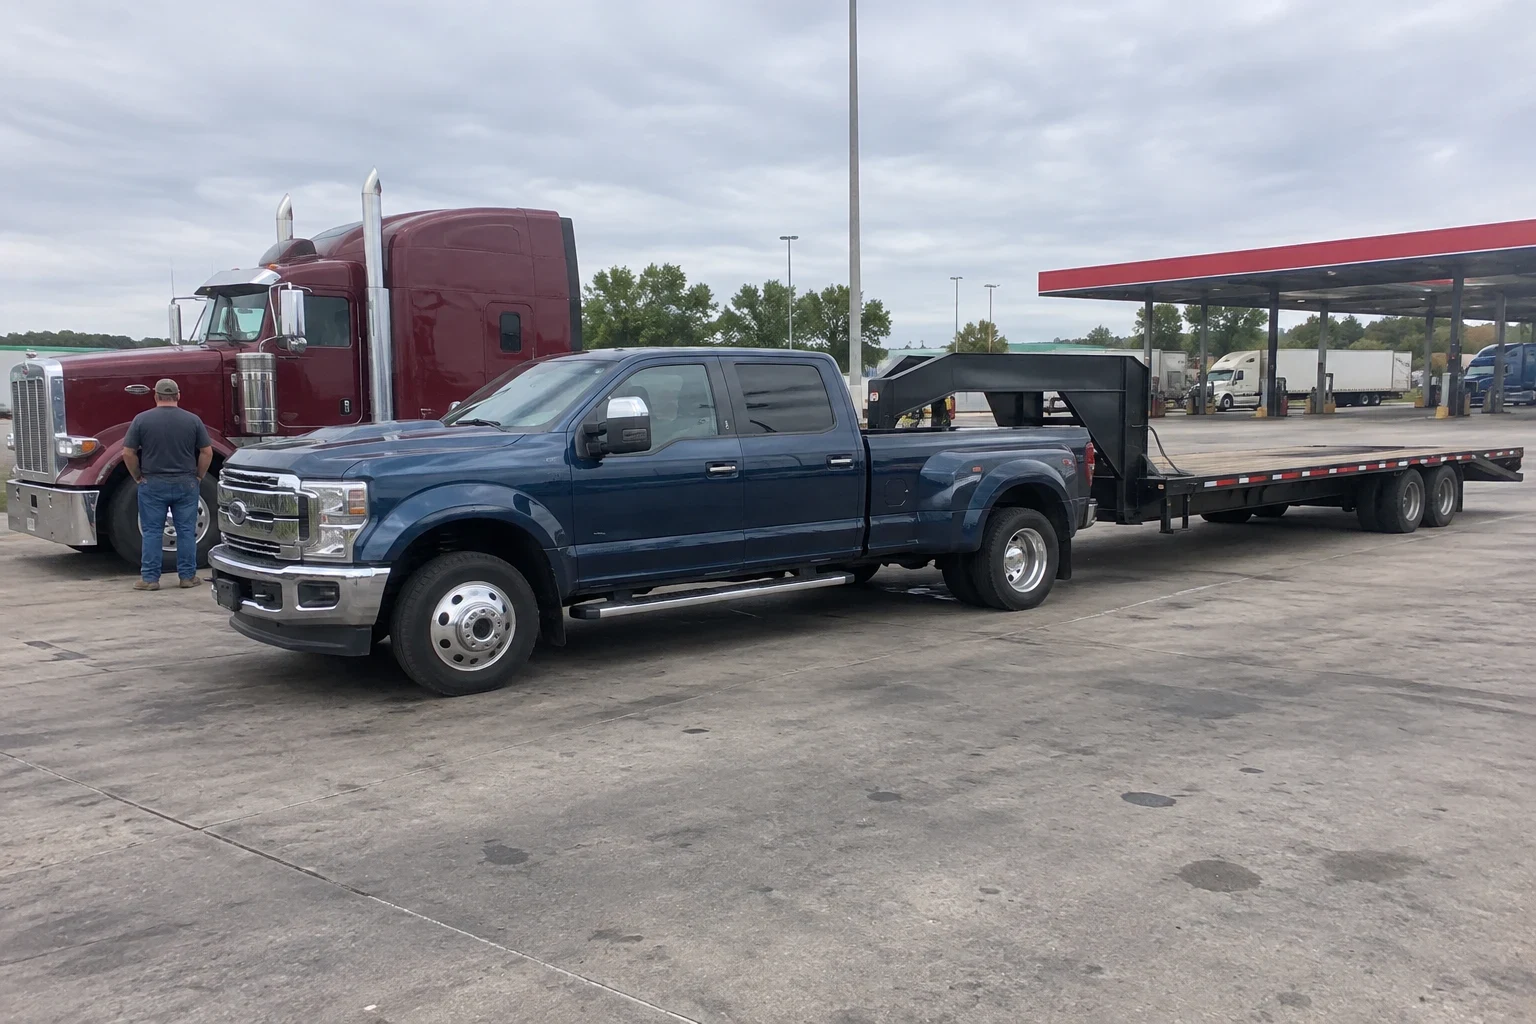
Running a one-ton pickup and a gooseneck takes the right mix of liability, cargo and physical damage coverage. We look at what you already carry, fix the gaps where we can, and build a policy that gets you approved with brokers and paid on loads.
Coverage for the Truck, the Trailer and the Load
A hotshot setup sits in an odd middle spot. The truck looks like a pickup, but the work is for-hire freight, so a personal auto policy will not respond to a claim on a paid load. Once your combined weight passes 10,001 pounds and you haul across state lines, you need MC authority, a DOT number and federal liability filings on record before you can dispatch.
Our first move is to read the policy you have now. If it can be fixed with an endorsement, a corrected trailer listing or a higher cargo limit, we tell you that plainly instead of starting over. When the carrier simply does not write hotshot well, we explain why a new policy makes more sense and what changes. We are licensed for property and casualty insurance and work with operators from Denton out to Krum, Ponder and Argyle, at our office or by phone and video.
The Pieces of a Hotshot Policy
Primary auto liability
This is the coverage that answers when you injure someone or damage their property while running a load. Federal rules require at least $750,000 for general freight, and plenty of brokers will not book you under $1 million.
Motor truck cargo
Protects the freight strapped to your deck against loss or damage. We read the commodity list and the securement language line by line, since machinery, pipe and oilfield parts are common hotshot loads and common spots for exclusions.
Physical damage on the pickup and trailer
Collision and comprehensive for the truck and for the gooseneck or bumper-pull, with a separate value on each. We often find a trailer that never made it onto the schedule, and that is an easy gap to close.
Federal filings and the MCS-90
Your insurance company files proof of coverage with FMCSA so your authority can activate and remain active. We check that the filing actually shows up and chase it if it sits.
Certificates for brokers and shippers
No certificate, no pickup. We issue them with the right limits and the right certificate holder named, so a load does not stall over a paperwork mistake.
Signs Your Hotshot Coverage Needs a Look
The pickup is on a personal auto policy
A personal policy is not written for paid freight, so a claim on a load can be turned down entirely. This is one case where a patch will not work and a commercial policy is the right move.
A broker turned down your certificate
A cargo limit that is too low, missing certificate holder wording or the wrong carrier name will stop you at setup. An endorsement on your current policy often clears it up within days.
You added or upgraded a trailer
A longer gooseneck or a second trailer has to be listed with its value. Until it is, damage to that trailer may not be paid.
Your freight is different now
Switching from general freight to equipment, vehicles or building materials can fall outside the cargo wording you have. We compare the exclusions to what you really haul.
Your renewal jumped without an explanation
A big increase should come with a reason. We go through your MVR, claims history and rating details to find what changed.
How We Work Through Your Hotshot Coverage
- 1
Start with how you run
We want to hear about your truck, your trailer, the freight you usually haul, your lanes and who else drives. Meet us in person at our office, or we can talk it through over the phone or on a video call.
- 2
Go through your current policy
Bring your declarations page along with any broker setup requirements. We point out what already works, what is missing and whether your current policy can be adjusted to cover it.
- 3
Adjust or switch, with reasons
When a change to the policy you have solves the problem, that is what we recommend. When it will not, we lay a new option next to your current one so you can compare the coverage and the premium plainly.
- 4
Get the paperwork moving
After coverage is bound, we confirm the federal filing lands with FMCSA and get certificates to your brokers. Five years in business has shown us where these steps usually hang up, so we watch those spots.
What Moves a Hotshot Premium
Hotshot work has no single rate. Underwriters weigh the driver, the rig and the freight as one package, so two setups that look alike on the road can be priced very differently. We show you which pieces are pushing your number up and which ones you have some control over.
- Your driving record and time in a CDL seat
- Tickets, at-fault accidents and how long you have driven commercially carry a lot of weight. A clean MVR and a few seasons of experience do more for the price than nearly anything else.
- How long your authority has been active
- A fresh MC authority tends to cost more in its first year or two. Running claim-free on that authority helps bring the premium down at later renewals.
- The freight and the miles
- Expensive or awkward loads that are hard to strap down push cargo rates higher. Long interstate lanes are rated differently than short regional runs close to home base.
- What the pickup and trailer are worth
- The physical damage portion is priced off the values you list for the truck and the gooseneck. Choosing a higher deductible trims the premium, as long as you could cover that amount yourself after a loss.
- Broker limit requirements
- Bumping liability to $1 million or lifting cargo to meet a broker's minimum adds to the bill. We set limits around the loads you actually take so you are not paying for coverage you never use.
Hotshot Insurance Questions
Something not covered here? (940) 267-2913
Do I need my own authority to run hotshot?
If you haul for-hire freight interstate with a combined weight over 10,001 pounds, you either need your own MC authority and DOT number or you lease onto a carrier that has one. If you lease on, the carrier's liability usually covers you under dispatch, and you would look at non-trucking liability and physical damage for your own rig. We can help you sort out which situation fits.
Can I keep my current policy and just add cargo?
Often yes, if your liability is already written as commercial for-hire coverage. We check that first, because adding cargo to a policy that is rated wrong does not solve the bigger problem. If it is set up correctly, a cargo add-on is usually the simplest fix.
Is my gooseneck covered automatically?
Not always. Liability may extend to a trailer while it is hooked up, but physical damage generally only covers trailers listed on the policy with a value. We make sure every trailer you pull is on the schedule.
How long until brokers get my certificate?
Once the policy is bound, we send certificates as soon as you give us the broker details. The federal filing is handled by the insurance company and can take a little time to show on FMCSA's system, so we watch for it and let you know when it posts.
I use the pickup on weekends too. Does that matter?
It matters for how the policy is written. Personal use can often be handled on the commercial policy, but it needs to be disclosed so a claim is not questioned later. Tell us how you use the truck and we will set it up honestly.
Let's Look at Your Hotshot Policy Together
Bring your declarations page and the limits your brokers want. We will tell you what can be fixed on the policy you have and when a new one makes more sense.